For most U.S. taxpayers, emotional support animal costs are not tax-deductible, according to IRS Publication 502. The IRS allows medical deductions for guide dogs and other service animals that are specially trained to perform tasks for a disability, but it treats emotional support alone as a personal expense. Any deduction also depends on itemizing and clearing the 7.5% of AGI threshold, plus solid documentation tying the cost to treatment.
TL;DR:
- Keep diagnoses, treatment recommendations, task training records, and dated receipts for at least three years; generic ESA letters and ID cards carry little tax weight.
- You must itemize on Schedule A, subtract insurance reimbursements, and claim only qualifying medical costs above 7.5% of adjusted gross income.
- If an animal later learns a documented task tied to a diagnosed disability, costs from that point forward may qualify, including training and care.
- Canada also excludes animals providing emotional support alone, while specially trained animals assisting someone with a severe impairment may qualify under CRA rules.
Table of Contents
- How U.S. tax rules treat ESAs versus service animals
- Documentation, evidence, and common proof readers will need
- How itemizing and the 7.5% of AGI threshold affect claims
- Concrete examples and scenarios
- A short note on Canada’s CRA rules
- What to do next this tax year
- A note from our editorial team
- How we can help with a legitimate ESA letter
- FAQ
- Sources
How U.S. tax rules treat ESAs versus service animals
The IRS draws a sharp line between animals trained to perform specific tasks and animals that offer comfort through their presence. Publication 502 lists costs for guide dogs or other service animals as a qualifying medical expense, covering the animal’s purchase, training, and upkeep when it assists someone with a disability. Emotional support animals do not appear in that category because they are not trained to perform a specific job tied to a medical condition. They provide comfort, which the IRS generally classifies as a personal benefit rather than medical care.
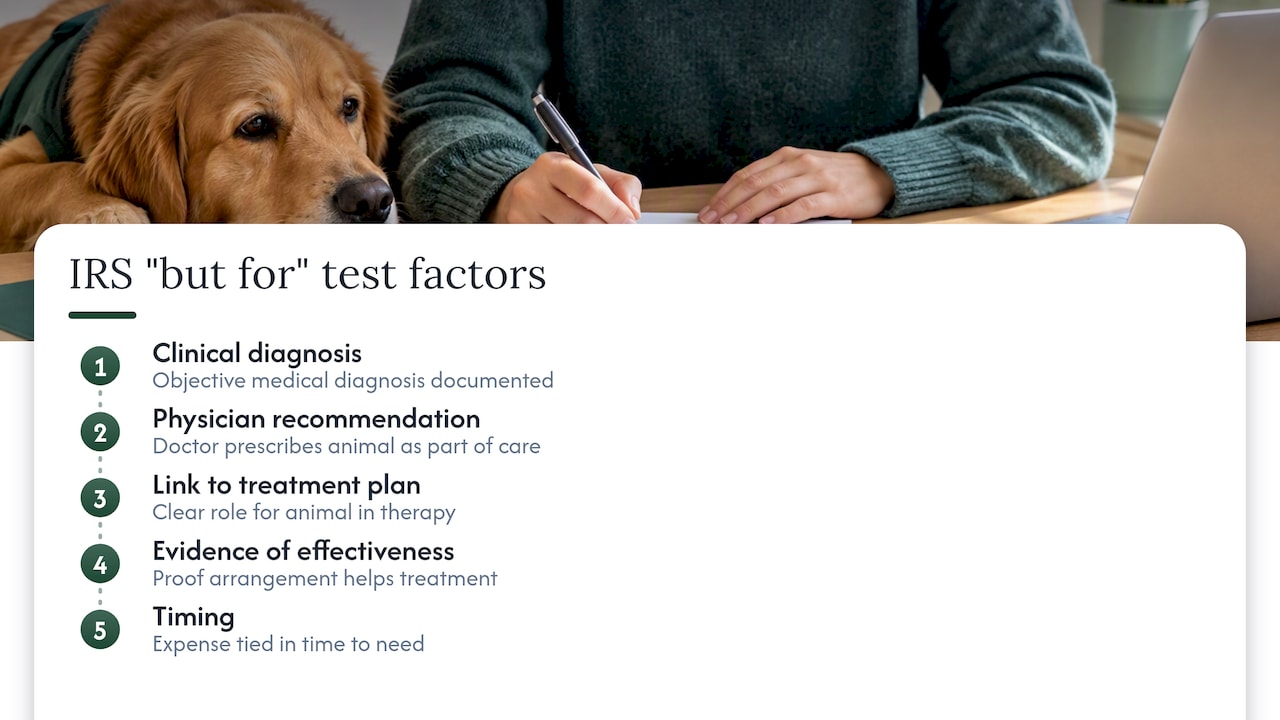
That distinction rests on what the IRS calls the “primarily for medical care” standard. Under written guidance the IRS issued in 2010, an expense qualifies as medical care only if the taxpayer can show it had not been paid “but for” the illness or disability, a test courts apply using objective factors: a clinical diagnosis, a physician’s recommendation, a clear link between the animal and the treatment plan, evidence the arrangement is effective, and timing that connects the expense to the medical need. The same guidance points to cases like Havey v. Commissioner and Commissioner v. Jacobs as the backbone of this analysis.
Comfort alone rarely survives that test. An animal that is not trained to perform a task, and whose connection to treatment is described only in general terms, looks more like a personal choice than a medical necessity in the IRS’s eyes. That is why most ESA-related costs, however real the mental health benefit, fall outside what the agency considers deductible medical care.
Documentation, evidence, and common proof readers will need
A tax claim lives or dies on paper. If you are hoping to build a case that an animal-related expense counts as medical care, certain records carry real weight:
- A written diagnosis from a licensed clinician that names the condition the animal is meant to address.
- Treatment notes that specifically recommend the animal as part of a care plan, not just a passing mention.
- Training receipts showing the animal learned to perform defined tasks connected to the disability.
- Invoices and receipts dated close to the treatment period, so the expense and the medical need line up in time.
A generic ESA letter, by contrast, is usually weak evidence on its own. It can establish that a clinician supports the animal’s presence in your life, which matters for housing and travel protections, but it rarely documents the task-based training or the “but for” linkage the IRS looks for in a medical deduction. The same goes for registration certificates or ID cards: they carry no legal weight with the IRS at all.
Keep every record that ties a cost to a specific treatment episode, and hold onto them for at least three years, the standard window the IRS can audit a return.
Pro Tip: Ask your treating clinician to date and specify their recommendation in the medical record itself, not just in the letter you carry day to day.
How itemizing and the 7.5% of AGI threshold affect claims
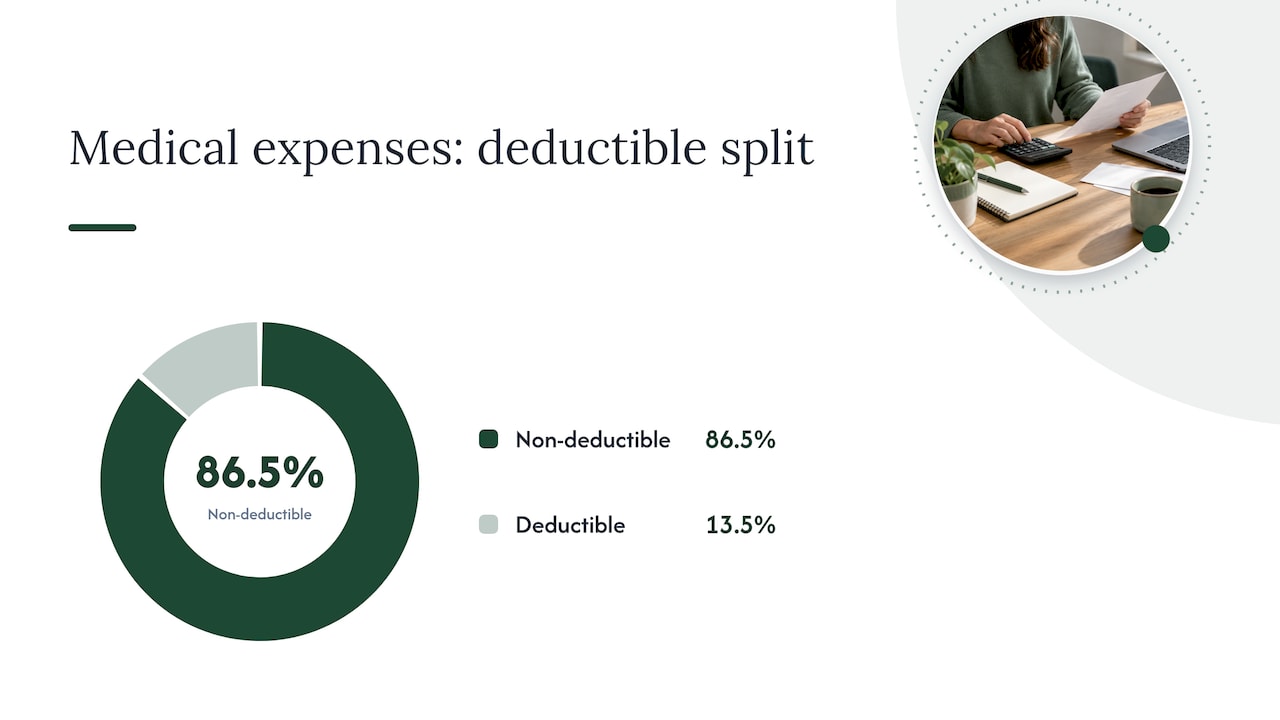
Even a well-documented expense only matters on your tax return if you itemize deductions instead of taking the standard deduction. According to Topic No. 502, medical expenses are deductible only to the extent they exceed a threshold percentage of your adjusted gross income, and any amount reimbursed by insurance has to be subtracted first.
Here is how that math plays out:
- Add up all qualifying medical expenses for the year, including any task-trained service animal costs.
- Subtract any insurance reimbursement you received for those expenses.
- Multiply your adjusted gross income by 7.5% to find your threshold.
- Deduct only the amount that exceeds that threshold on Schedule A.
Say your AGI is $60,000: your threshold is $4,500. If your total qualifying medical expenses for the year come to $5,200, you could deduct $700, the amount above the threshold. Many taxpayers with otherwise modest medical costs find that even a legitimate service animal expense doesn’t push them past this line, which is one more reason ESA-only costs rarely make a dent.
Concrete examples and scenarios
A few scenarios show how this plays out in practice:
- A person with epilepsy has a dog specially trained to detect and respond to seizures. The dog’s purchase price, training costs, food, and veterinary care may qualify as medical expenses, backed by a physician’s diagnosis and documentation of the training program.
- A person with generalized anxiety keeps a cat recommended by a therapist purely for comfort, with no task training involved. The cat’s food, vet bills, and acquisition cost generally fail the IRS test because there is no trained function tied to the diagnosis.
- A person starts with an ESA for anxiety, then enrolls the animal in a certified training program that teaches it to interrupt panic attacks through a specific trained behavior. Once that training is documented, the animal may shift from “comfort only” to “service animal,” and related costs from that point forward have a stronger case.
Every situation turns on its own facts, so a tax professional who can review your specific records is worth consulting before you claim anything unusual on a return.
A short note on Canada’s CRA rules
Canada draws a similar line. CRA medical expense guidance states that an animal providing only emotional support, without specialized training for a specific task, is not eligible as a medical expense. An animal specially trained to assist someone with a severe impairment may qualify, and eligible costs can include care, maintenance, and travel connected to training. Readers outside the United States and Canada should check with their own national tax authority, since rules vary widely by country.
What to do next this tax year
If you want to explore whether any ESA or service-animal-related cost might qualify, start with a short checklist:
- Gather medical records that document your diagnosis and the clinician’s specific recommendation.
- Keep every invoice and receipt tied to the animal’s acquisition, training, or care.
- Ask your clinician to describe, in writing, any trained behavior the animal performs for your condition, not just the general benefit of its company.
- Track insurance reimbursements separately, since they reduce what you can claim.
Pro Tip: If your expenses are substantial and your situation is unusual, a tax preparer or accountant can tell you whether it’s worth requesting a private letter ruling from the IRS before you file.
A note from our editorial team
We built our site to cut through confusion around emotional support animals, from qualifying for one to spotting the scams that plague this space. ESAs offer real comfort to people managing anxiety, depression, PTSD, and other conditions, but tax deductibility is a narrow legal question reserved mostly for task-trained service animals. We keep our guidance grounded in what the rules actually say, not what’s easiest to hear.
— Erik
How we can help with a legitimate ESA letter
We focus on what we know best: helping you get a valid ESA letter from a licensed clinician, understand your housing rights under the Fair Housing Act, and avoid the registration scams that flood this space. We are not a tax advisor, so for anything tax-specific, talk to a qualified tax professional who can look at your full return.
- Learn what makes an ESA letter legitimate versus a scam.
- Understand your protections as a renter with an ESA.
- Get clear, plain-language answers before you pay for anything.
Start with our emotional support animal guide to see what a properly documented ESA letter looks like and how to move forward with confidence.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Is an ESA letter itself tax-deductible?
The cost of obtaining an ESA letter, including the evaluation fee, is generally not deductible because the letter alone does not establish the “primarily for medical care” standard the IRS requires. It can support housing and travel accommodations, but it rarely functions as proof for a tax deduction on its own.
Can I deduct veterinary bills for my emotional support animal?
Veterinary fees for an ESA are generally not deductible under IRS rules, since they are treated as personal pet expenses rather than medical care. Veterinary costs tied to a specially trained service animal may qualify, provided the animal performs a defined task connected to a disability.
What form do I use to claim an eligible animal expense?
Eligible medical expenses, including qualifying service animal costs, are reported on Schedule A as itemized deductions, and only the portion exceeding 7.5% of your adjusted gross income counts according to IRS Topic No. 502. You cannot claim this if you take the standard deduction instead of itemizing.
Does training an ESA to perform tasks change its tax status?
Yes, an animal that is specially trained to perform specific tasks for a diagnosed disability can shift from “emotional support only” toward the service animal category the IRS recognizes for medical deductions. The key is documented training tied to a specific function, not just companionship.
Are the rules different in Canada?
Yes, the Canada Revenue Agency also excludes emotional-support-only animals from medical expense claims, but allows costs for animals specially trained to assist with a severe impairment. Canadian readers should confirm specifics with the CRA or a Canadian tax professional.